
Top 5 Lenders for a 620 Credit Score Personal Loan in 2026
Last updated: 2026-11-08
Trying to find a loan with a 620 credit score can feel like driving through a thick fog without a compass. You know the money exists, but finding a lender that sees your score as a starting point rather than a dead end is difficult. This specific number lands you in that tricky “fair” territory where many doors start to close.
When shopping for cash, the monthly payment is only half the story. A lender might promise low installments, but hidden fees or aggressive interest rates can turn a small loan into a massive financial weight. You have to look past the shiny marketing and dig into the fine print before signing anything.
- Happy Money
- JetzLoan
- Mariner Finance
- NetCredit
- Navy Federal Credit Union
How These Lenders Were Evaluated for Fair Credit Borrowers
We focused on finding lenders that actually cater to the “fair credit” crowd. It isn’t enough to just be available; a lender has to be clear about interest rates and how likely you are to get approved. We looked for companies that make decisions quickly, which is vital if you are facing urgent home repairs or sudden life expenses.
Protecting your score while you shop was another priority. We looked for lenders that offer soft credit inquiries for initial rate checks. If a lender hits your credit report with a hard inquiry every time you check a rate, they are making it much harder for you to find a good deal without damaging your score.
| Lender Name | Loan Amount | Terms | Interest Rate (APR) | Credit Check Impact |
|---|---|---|---|---|
| Happy Money | $5,000 – $50,000 | 24 – 84 months | 8.95% – 35.99% | No impact to check rate |
| JetzLoan | see site | see site | see site | see site |
| Mariner Finance | Up to $25,000 | see site | see site | No impact to check offers |
| NetCredit | Up to $10,000 | Flexible | see site | No impact to check eligibility |
| Navy Federal Credit Union | see site | see site | see site | see site |
Ranking of the Best Lenders for 620 Credit Scores
1. Happy Money

Happy Money works well for people trying to escape a cycle of credit card debt. Instead of chasing several different high-interest bills, you can roll them into one single, fixed monthly payment. Having a clear end date for your debt can provide a massive psychological relief when you feel overwhelmed by interest.
This platform is a strong option if you need a larger chunk of cash, specifically between $5,000 and $50,000. With rates starting at 8.95% APR, it functions as a practical tool for debt consolidation. Just keep in mind that an origination fee between 2% and 12% is taken out of your loan upfront.
Pros:
- Fixed monthly payments with a set payoff date.
- Potential to save thousands in interest through consolidation.
- Checking rates is free and does not impact your credit score.
Cons:
- Origination fees reduce the actual cash you receive.
- Lower credit scores may face higher APRs.
2. JetzLoan
JetzLoan is a specialized choice for anyone wanting a purely digital experience. They occupy a niche space, focusing on getting capital into your hands without the usual banking headaches. It is a streamlined solution for borrowers who prioritize speed above almost everything else. (jetzloan.com)
If you need funds for a specific, time-sensitive project, this lender might fit your needs. Because they are more specialized, you have to read their terms carefully to ensure they work for your long-term goals. Always check the total cost of the loan before you sign anything.
Pros:
- Fast, digital-first application process.
- Designed for quick deployment of funds.
- Minimal paperwork compared to traditional banks.
Cons:
- Limited availability of specific loan terms.
- Rates may not be the lowest for top-tier borrowers.
3. Mariner Finance
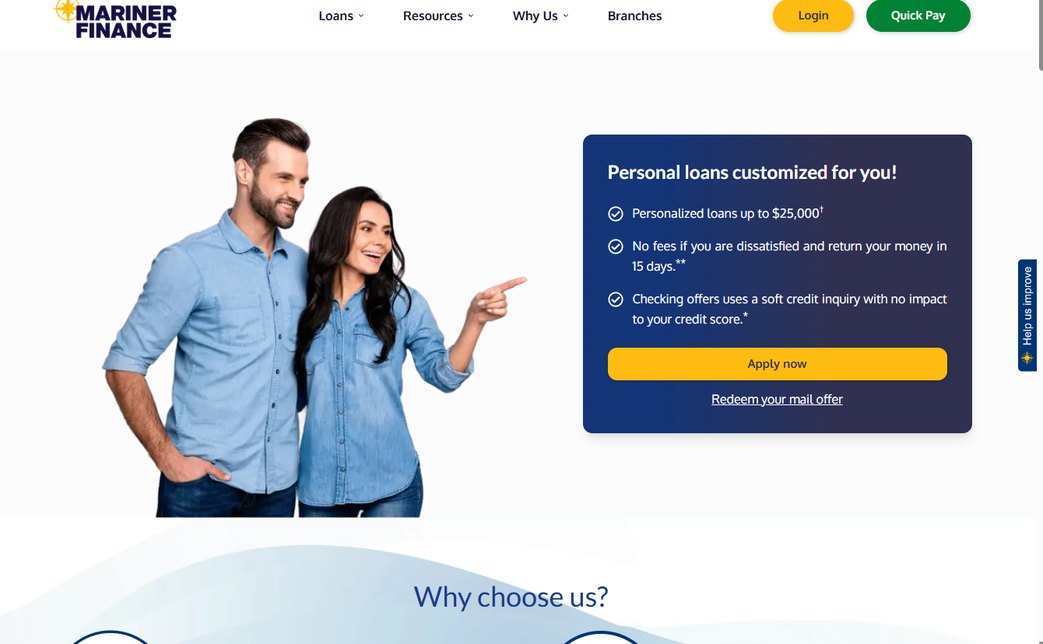
Mariner Finance is a major player in community lending and offers a more personal touch. They provide loans up to $25,000 and include a unique satisfaction guarantee. If you aren’t happy with the terms, you can return the money within 15 days to avoid fees, which is a rare safety net.
The application process is incredibly fast, often taking less than five minutes online. This is great if you want to see your options without committing to a hard credit pull. They try to tailor offers to your specific needs, making them a solid choice for those with fair credit.
Pros:
- 15-day satisfaction guarantee with no fees if returned.
- Extremely fast application process.
- Soft credit inquiry to check offers without impact.
Cons:
- The guarantee requires you to return the full amount quickly.
- Physical branches aren’t available in every single location.
4. NetCredit
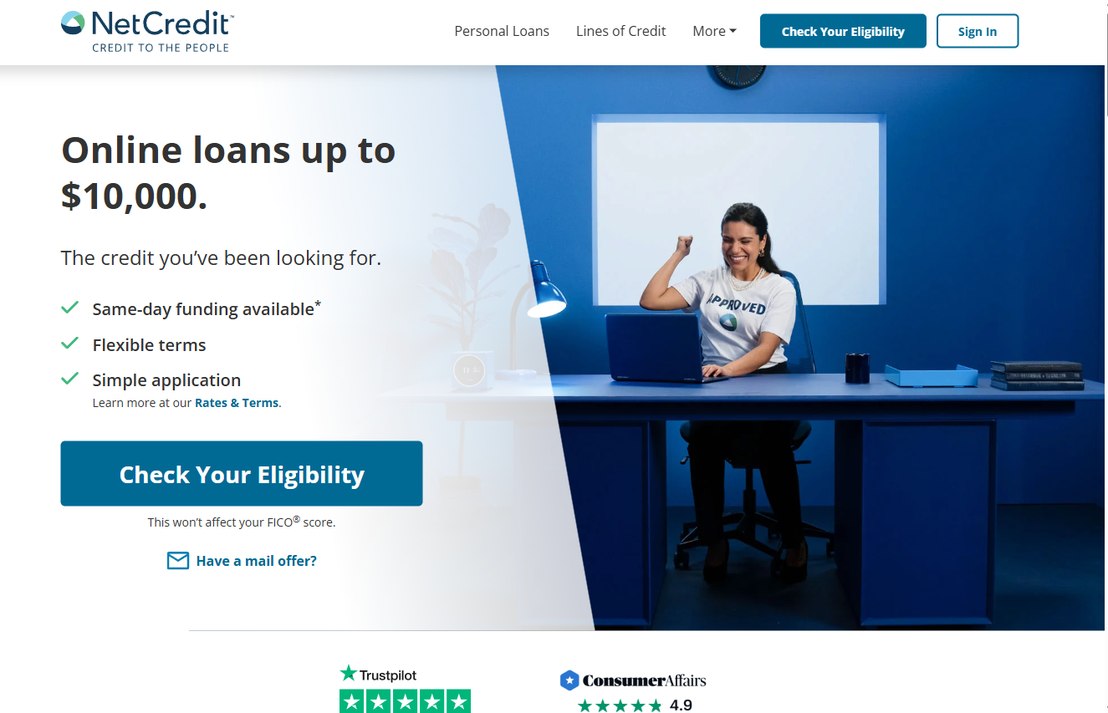
NetCredit operates on the idea that you are more than just a number in a database. They use algorithms that look past a simple FICO score, which is a huge advantage for someone sitting at a 620. This approach helps them see potential in borrowers that a traditional bank might reject immediately.
If you are in a pinch, they offer same-day funding to help bridge the gap. Their loans and lines of credit go up to $10,000, making them a good pick for smaller, urgent needs. They partner with established banks to keep the underwriting process reliable.
Pros:
- Same-day funding available for quick cash access.
- Underwriting looks beyond just your credit score.
- Flexible terms to match your repayment capabilities.
Cons:
- Loan amounts are capped at a modest $10,000.
- Interest rates vary significantly based on the algorithm.
5. Navy Federal Credit Union
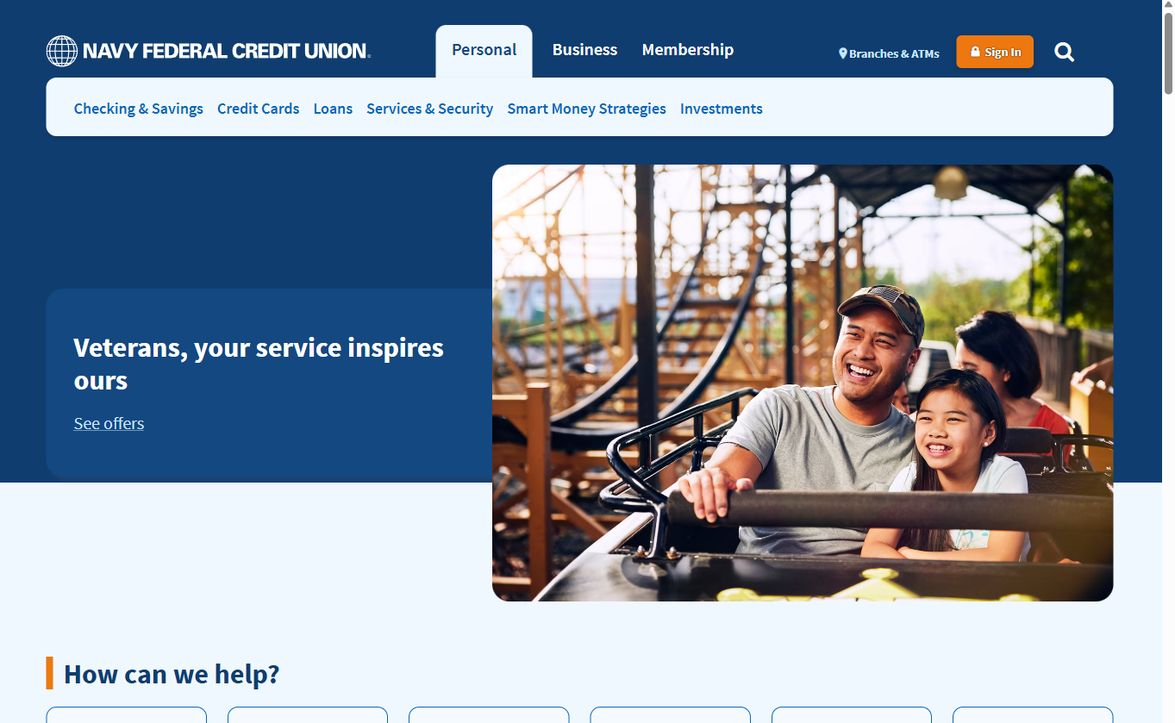
Navy Federal Credit Union is an excellent choice, but there is a catch: you have to qualify for membership. If you are a veteran or have a military connection, you are looking at one of the best institutions available. Their products are built specifically to serve those who serve the country.
They offer everything from auto loans to credit cards and personal loans. One standout feature is the 90-day preapproval window, which gives you plenty of time to decide if the loan fits your budget. It is a very stable option for those who meet the membership requirements.
Pros:
- Extremely competitive rates for members.
- 90-day preapproval window provides flexibility.
- Wide range of financial services beyond personal loans.
Cons:
- Membership is restricted to military-affiliated individuals.
- Approval processes can be more stringent than specialized lenders.
Navigating Your Path to Approval
Getting a loan with a 620 score requires a bit of a strategy. One way to boost your chances is to find a cosigner. Adding someone with better credit to your application can help you get a larger loan and, more importantly, a much lower interest rate. You are essentially using their reputation to strengthen your own.
Providing collateral is another smart move. While many personal loans are unsecured, offering an asset as backing can lower the lender’s risk significantly. If you have a vehicle or other valuable property, it might be the key to unlocking much better terms, though you risk losing that asset if you can’t pay.
Don’t rush into the first offer you see. It is easy to get excited by “instant approval” messages, but that is often when the most expensive loans are sold. Compare the APR, not just the monthly payment. A low monthly payment on a 72-month loan can actually cost you far more than a higher payment on a 36-month loan.
Finally, keep an eye on your debt-to-income ratio. Even with a 620 score, lenders will see you as high-risk if your monthly obligations are too high. Before you apply, try to pay down small balances to lower your credit utilization. That small shift can sometimes nudge your score into a higher bracket, saving you hundreds in interest.