
Top 6 Lenders for Loans for Bad Credit in 2026 Ranked
Last updated: 2026-11-08
Walking into a bank with a bruised credit score often feels like trying to enter a VIP club with a revoked membership card. You know the money is there, but the gatekeepers seem to look right through you. It is a frustrating dance of denials and “no” that can leave anyone feeling stuck in a financial rut.
The psychological toll of a denied loan application can be just as heavy as the financial one. This creates a sense of hopelessness that makes the climb back to solvency feel insurmountable. It is hard to stay motivated when every door seems to slam shut before you even get a chance to speak.
Finding a way out requires more than just hope; it requires knowing which lenders actually look at the person behind the number. Relying on a single “quick fix” often leads back to the same cycle of high-interest debt. Instead, successful borrowers look for strategic partnerships.
This ranking highlights the most reliable options available this year for those navigating the tricky waters of subprime lending and non-traditional credit requirements. Whether you are facing a sudden medical emergency, looking to consolidate high-interest credit card debt, or trying to bridge the gap between freelance paychecks, choosing the right institution is the first step toward long-term stability.
- Coast Line Credit Union
- SoFi
- JetzLoan
- Citi
- Giggle Finance
- Avant
How These Lenders Were Evaluated
The selection process focused on accessibility and the specific needs of borrowers who do not fit the standard “prime” profile. It is not just about who will say yes, but who provides the most transparent terms and reasonable paths toward financial recovery. Finding a lender that understands the nuances of a non-traditional income is vital.
For example, a traditional lender might see a fluctuating monthly income from an Uber driver or a freelance designer as a “risk.” A specialized lender, however, sees it as a predictable pattern of cash flow. This distinction can make or break an application for anyone working in the gig economy.
Every entry was scrutinized based on their ability to serve diverse populations, including the self-employed and those with limited history. We looked beyond the surface-level marketing to determine if their approval algorithms account for alternative data, such as rent payments or utility bills, which can be life-changing for those with thin credit files.
Speed of funding, ease of the application process, and the breadth of available products were the primary lenses used to determine where each lender sits in this list. Accuracy remains the cornerstone of this editorial review, ensuring that borrowers have a clear roadmap rather than a collection of broken promises.
| Lender Name | Max Loan Amount | Funding Speed | Target Audience | Requirements |
|---|---|---|---|---|
| Coast Line Credit Union | see site | see site | Members | see site |
| SoFi | see site | see site | High earners/Professionals | see site |
| JetzLoan | see site | see site | see site | see site |
| Citi | see site | see site | General Consumers | see site |
| Giggle Finance | $15,000 | Minutes | Side hustlers/1099s | see site |
| Avant | see site | see site | Credit rebuilding | see site |
The Best Lenders for Tough Credit Situations
1. Coast Line Credit Union
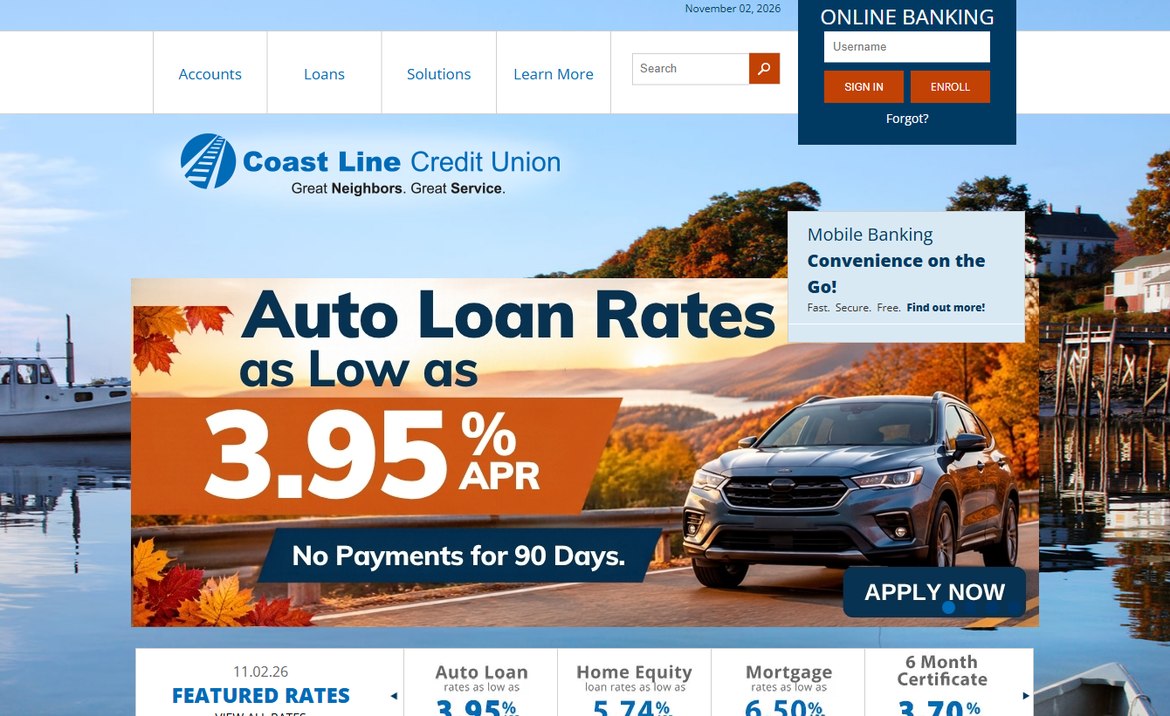
Credit unions often act as a sanctuary for those who find big banks a bit too cold and unyielding. Coast Line Credit Union operates with a community-focused mindset, offering a variety of loans and financial solutions that might feel more personal than a standard corporate transaction. Unlike large national banks that rely heavily on automated, rigid scoring models, credit unions are member-owned cooperatives.
This structure often allows for more human intervention in the decision-making process. It is an ideal setting for individuals who prefer a structured, member-based environment. Because they focus on a range of solutions, they might offer a more nuanced view of a borrower’s financial health than a purely algorithmic lender would allow.
If you have a unique situation—perhaps a recent job change or a medical event that temporarily impacted your score—the ability to speak with a loan officer who understands local economic realities can be the difference between a rejection and an approval. Personal connection matters when the numbers don’t tell the whole story.
Pros:- Community-oriented approach
- Variety of financial solutions
- Established institutional stability
- Membership requirements may apply
2. SoFi
SoFi is a powerhouse in the modern fintech landscape, catering heavily to those who are on an upward trajectory. While they are often associated with high-earning professionals, their ecosystem of banking, investing, and lending provides a comprehensive suite of tools for managing wealth. They have mastered the art of the digital-first experience, allowing users to manage their entire financial life from a single, highly polished mobile application.
If you are looking to move beyond just surviving and start actually building a financial fortress, SoFi offers the high-yield savings and investment tools to make that happen. They are perfect for the person who has a steady income but might be working on their score. Their loans are often designed for consolidation, allowing you to take several high-interest debts and roll them into one single, lower-interest monthly payment.
This can dramatically improve your monthly cash flow. Instead of chasing five different due dates every month, you focus on one. It simplifies your mental load and helps you see exactly where your money is going each month.
Pros:- Comprehensive financial ecosystem
- High-yield savings options
- Integrated investment tools
- May require higher income benchmarks
3. JetzLoan
JetzLoan positions itself as a streamlined option for those who cannot afford to wait around for bureaucratic red tape. In a world where timing is everything, having a lender that focuses on the speed of the transaction can be a lifesaver during an emergency. When your car’s transmission fails or a sudden home repair threatens your stability, you don’t have three weeks to wait for a traditional bank to process paperwork. (jetzloan.com)
This lender suits the individual who needs a quick injection of cash and wants a digital-first experience. The application process is designed to be frictionless, minimizing the number of steps between your initial inquiry and the decision. It is built for the modern borrower who values efficiency and a no-nonsense approach to the application process.
It is a go-to for those in urgent, short-term need of liquidity. When you are in a pinch, you need a solution that works as fast as the problem arose. JetzLoan aims to be that immediate response.
Pros:- Fast application process
- Digital-centric interface
- Targeted at quick funding
- Limited product variety
4. Citi
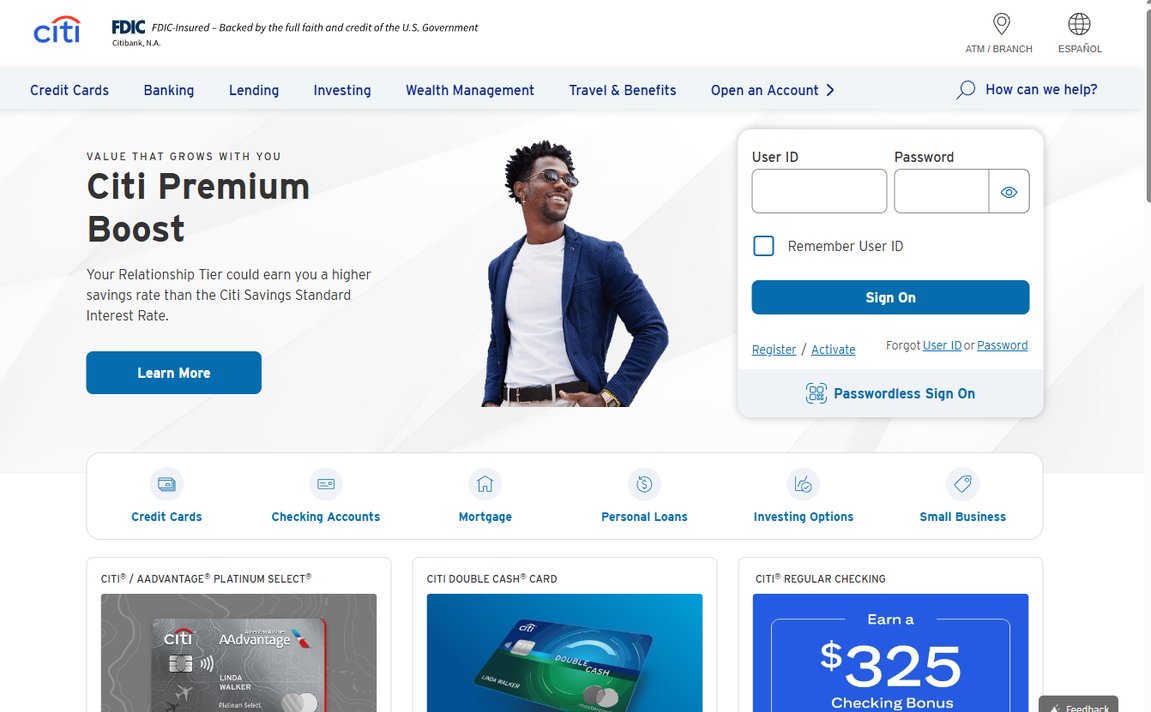
Citi is a titan of the industry, offering a massive array of products from mortgages to personal loans. They are a one-stop shop for anyone looking to manage their entire financial life under one roof, providing everything from credit cards to wealth management. Because of their sheer size, they have the capital to support a vast range of consumer needs, making them a cornerstone of the global financial system.
For a borrower looking to rebuild their relationship with a major institution, Citi offers the scale and stability that smaller lenders simply cannot match. They are a solid choice for those who want to consolidate their financial presence with a global leader. While their entry requirements might be stricter than a subprime specialist, their long-term products can be incredibly useful.
Consider their premium credit cards with significant travel rewards. These can be instrumental in building a high-tier credit profile over time. It is a long game, but the rewards can make the effort worthwhile for the patient borrower.
Pros:- Global brand recognition
- Extensive product range
- Integrated banking and investing
- Strict traditional requirements
5. Giggle Finance
Giggle Finance is a breath of fresh air for the modern gig economy worker. They understand that a 1099 income or a side hustle doesn’t look like a traditional paycheck on paper, even though the money is very real. In the past, freelancers often faced “income instability” red flags from banks, but Giggle Finance looks at the consistency of earnings rather than just the format of the deposit.
This lender is a game-changer for contractors and small business owners who need up to $15,000 in minutes. They focus on the reality of modern work, providing quick funding for those who are building something of their own on their own terms. Whether you are a consultant, a creative professional, or a delivery driver, this lender provides the liquidity needed to manage the feast-or-famine nature of independent work.
They bridge the gap between the old way of banking and the new way of earning. If your income doesn’t arrive on a set schedule every two weeks, you need a lender that won’t penalize you for that reality.
Pros:- Specializes in 1099/side hustle income
- Extremely fast funding
- High loan amounts for repeat customers
- Niche focus may not suit traditional employees
6. Avant
Avant is built for the journey of financial movement. They recognize that everyone’s path is different, offering tools and solutions specifically designed to help people move forward, whether through debt consolidation or emergency loans. Their approach is predicated on the idea that a credit score is a snapshot in time, not a permanent definition of your character or your future potential.
This is an excellent choice for those who need flexible options to handle life’s unexpected curveballs. They provide a clear path for those who are actively working to improve their financial standing and need a partner in that process. By offering loans that specifically target the middle ground of credit, Avant serves a massive, often overlooked segment of the market.
These are people who aren’t quite “prime” but are moving in the right direction. It is about recognizing the potential in a borrower who is clearly making an effort to get back on track.
Pros:- Flexible loan solutions
- Focus on credit rebuilding
- User-friendly digital tools
- Interest rates can vary significantly
The True Cost of Credit
Before you commit to any loan, you must understand the concept of the Annual Percentage Rate (APR). While many borrowers focus solely on the monthly payment amount, the APR provides a more accurate picture of the total cost by including both the interest rate and any upfront fees associated with the loan. A lender might advertise a low monthly payment, but if that payment is stretched over five years and includes massive origination fees, you could end up paying double the amount you originally borrowed.
To calculate the true cost of your potential debt, perform a simple math exercise: take your total monthly payment, multiply it by the total number of months in the loan term, and then subtract the original loan amount. The resulting number is the “interest cost.” Compare this number across different lenders. A lender with a slightly higher interest rate but zero origination fees might actually be cheaper than a “low-interest” lender that charges a 5% fee upfront just to process the loan.
Strategic Steps to Increase Approval Odds
If you know your credit is currently suboptimal, you can take proactive steps to strengthen your application before you even submit it. These steps can move you from a “likely decline” to a “conditional approval.”
First, review your credit report for errors. It is surprisingly common for outdated collections or incorrect late payments to remain on a report, dragging down your score unfairly. Disputing these errors through the major credit bureaus can provide an immediate, albeit small, boost to your score. Second, focus on your credit utilization ratio. If your credit cards are maxed out, your score will suffer even if you have never missed a payment. Paying down even a small amount of these balances can improve your score enough to qualify for better interest rates.
Third, prepare a “financial narrative.” If you are applying for a loan to consolidate debt, be ready to explain how that consolidation will lead to better financial stability. If you are self-employed, have your last two years of tax returns and three months of bank statements organized and ready. Providing a lender with a clear, documented reason for the loan and a clear, documented ability to repay it builds trust and reduces the perceived risk of your application.
Finally, remember that your debt-to-income (DTI) ratio is a critical metric. Lenders look at your total monthly debt obligations divided by your gross monthly income. If your DTI is above 40%, many lenders will see you as overextended, regardless of your credit score. Before applying, try to pay down small, high-interest debts to lower your monthly obligations, thereby improving your DTI and making you a much more attractive candidate to both traditional and non-traditional lenders.
Navigating the world of lending requires a balance of urgency and caution. While it is tempting to grab the first offer that comes your way, the most successful borrowers are those who treat the process like a strategic negotiation rather than a desperate plea. By using the tools and lenders listed above, and by approaching your debt with a clear-eyed understanding of the costs, you can turn a financial setback into a stepping stone toward long-term prosperity.