
The 7 Best Options for Tractor Financing in 2026
Last updated: 2026-11-08
Securing the cash needed to run a farm or a landscaping business is a heavy lift. Whether you need a compact tractor for a small hobby farm or heavy-duty machinery for large-scale production, your loan terms can make or break a seasonal budget. The world of agricultural lending is vast and often confusing.
Finding the right lender involves more than just hunting for the lowest interest rate. You have to weigh the speed of funding against the flexibility of terms and the specific requirements of your credit profile. Some lenders cater to prime borrowers with high scores. Others focus on lease-to-own models to help those with less traditional financial histories get the tools they need.
- JetzLoan
- Kubota
- John Deere
- Farm Credit
- Koalafi
- LightStream
- United
How We Evaluated Agricultural Lending Options
We ranked these options by analyzing various lending models based on their accessibility and specific products. We looked at manufacturer-direct financing, which often provides specialized rates for specific brands, against general personal loans that offer more flexibility in how the funds are used. This distinction matters because it changes your collateral requirements and repayment structures.
The evaluation also considered the specific needs of different types of users. A professional contractor might prioritize quick funding and high loan amounts. A family-run farm might prioritize long-term stability and specialized agricultural credit. Each entity was judged on its transparency, the variety of its programs, and how well it serves the diverse spectrum of the American agricultural community.
| Lender | Key Terms/Rates | Loan Type | Credit Requirements |
|---|---|---|---|
| JetzLoan | see site | Lease-to-own/Payment plans | No credit or bad credit options |
| Kubota | 0% APR for up to 60 months or save up to $12,000 | Equipment financing | see site |
| John Deere | see site | Customized financing solutions | see site |
| Farm Credit | Reliable, consistent credit | Agricultural cooperative | see site |
| Koalafi | Lease-to-own options | Business financing | Up to 40% of U.S. adults lack traditional credit |
| LightStream | see site | Personal loans | see site |
| United | Rates as low as 5.99% APR* | Mortgage/Personal/Ag | see site |
Top-Rated Lenders for Your Equipment Needs
1. JetzLoan
This option is a lifesaver for those who find themselves stuck in the mud of traditional banking. If you are worried that a low credit score will keep you from the machinery you need, their flexible models are designed to bridge that gap. They focus on getting equipment into hands through accessible payment plans. (jetzloan.com)
The service is particularly suited for individuals or small businesses that might not meet the rigid standards of a major national bank. By offering lease-to-own structures, they provide a path toward ownership that is much more forgiving than a standard high-interest installment loan.
Pros:
- Designed for those with bad credit or no credit.
- Flexible lease-to-own and payment plan models.
- Helps acquire equipment without traditional hurdles.
Cons:
- Terms may be less favorable than prime bank rates.
2. Kubota
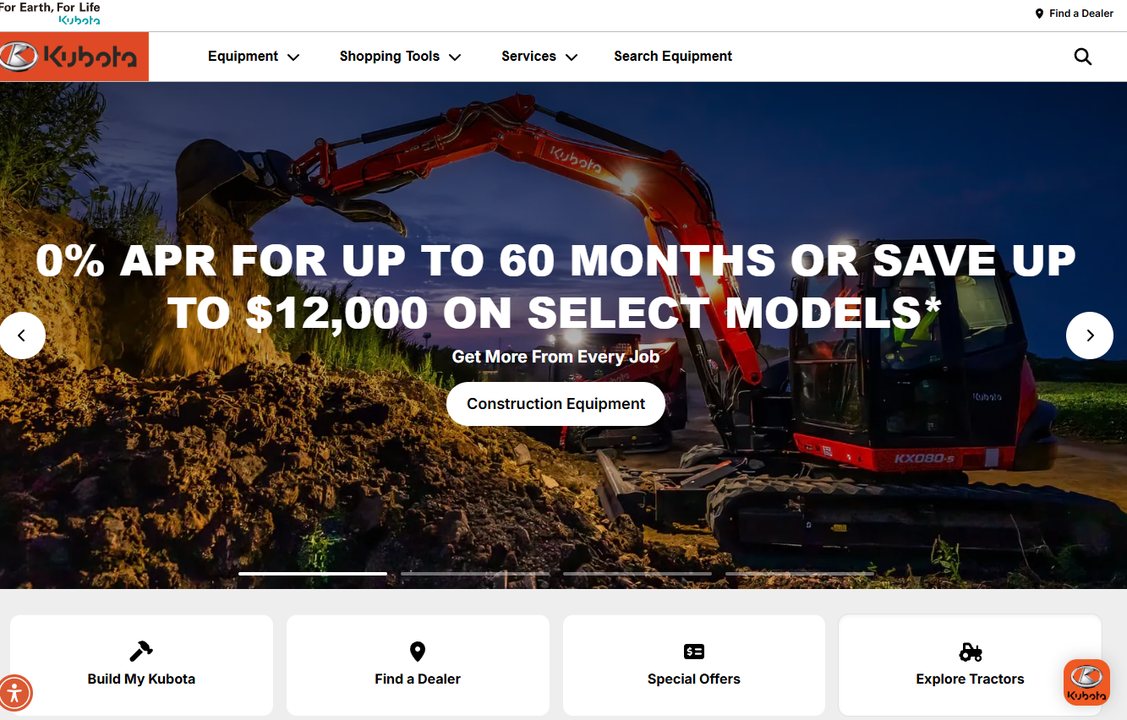
Kubota offers a direct line to financing that feels as integrated as the machines themselves. They provide very specific incentives, such as 0% APR for up to 60 months or significant savings of up to $12,000 on select models. This is a powerhouse for someone looking to maximize their purchasing power.
They also provide specialized options, like $0 down with 2.99% A.P.R. for 36 months on a new Kubota Sidekick. This level of tailoring makes it incredibly easy for a buyer to walk into a dealer and walk out with a machine that fits their specific cash flow needs.
Pros:
- Significant savings of up to $12,000 on select models.
- Attractive 0% APR options for up to 60 months.
- Low down payment options like $0 down on Sidekicks.
Cons:
- Offers are often tied to specific models and participating dealers.
3. John Deere
For nearly two centuries, John Deere has been a staple in the American landscape. Their financing is built around the idea of long-term partnership rather than a one-off transaction. They offer customized financing solutions that aim to help your specific operation succeed, whether you are a large-scale producer or a small operator.
They provide a range of solutions for everything from compact tractors to heavy-duty harvesting equipment. This variety ensures that the financing matches the scale of the machinery, providing a sense of security that comes from working with a massive, established industry leader.
Pros:
- Highly customized financing solutions for real-life operations.
- Deeply established brand with a massive support network.
- Options available for a wide variety of equipment types.
Cons:
- Standardized manufacturer terms may be less flexible than a local co-op.
4. Farm Credit
Farm Credit operates as a nationwide network of customer-owned cooperatives, which changes the entire dynamic of the relationship. They aren’t just a bank; they are a community-focused entity supporting over 615,000 farmers, ranchers, and agribusinesses across all 50 states and Puerto Rico.
This makes them a premier choice for those who want reliable and consistent credit that understands the seasonal nature of agriculture. Because they are customer-owned, the focus remains heavily on helping rural businesses grow and helping rural families thrive in their local communities.
Pros:
- Customer-owned cooperative structure.
- Specialized support for agricultural producers and rural businesses.
- Extensive nationwide presence with local roots.
Cons:
- Focus is strictly on agricultural and rural-related business.
5. Koalafi
Koalafi is an excellent tool for business growth, specifically designed to help merchants attract customers who might otherwise be unable to afford large purchases. They specialize in lease-to-own financing, which is a game-changer for non-prime shoppers looking to build their financial futures.
This lender is perfect for the business owner who wants to increase their average order value by offering more payment options. It allows for a long-term relationship with customers who may lack the credit needed for traditional, high-barrier financing methods.
Pros:
- Specifically helps convert non-prime shoppers into loyal customers.
- Facilitates lease-to-own models that drive business growth.
- Trusted by tens of thousands of merchant partners.
Cons:
- Primarily a merchant-driven platform rather than a direct consumer bank.
6. LightStream
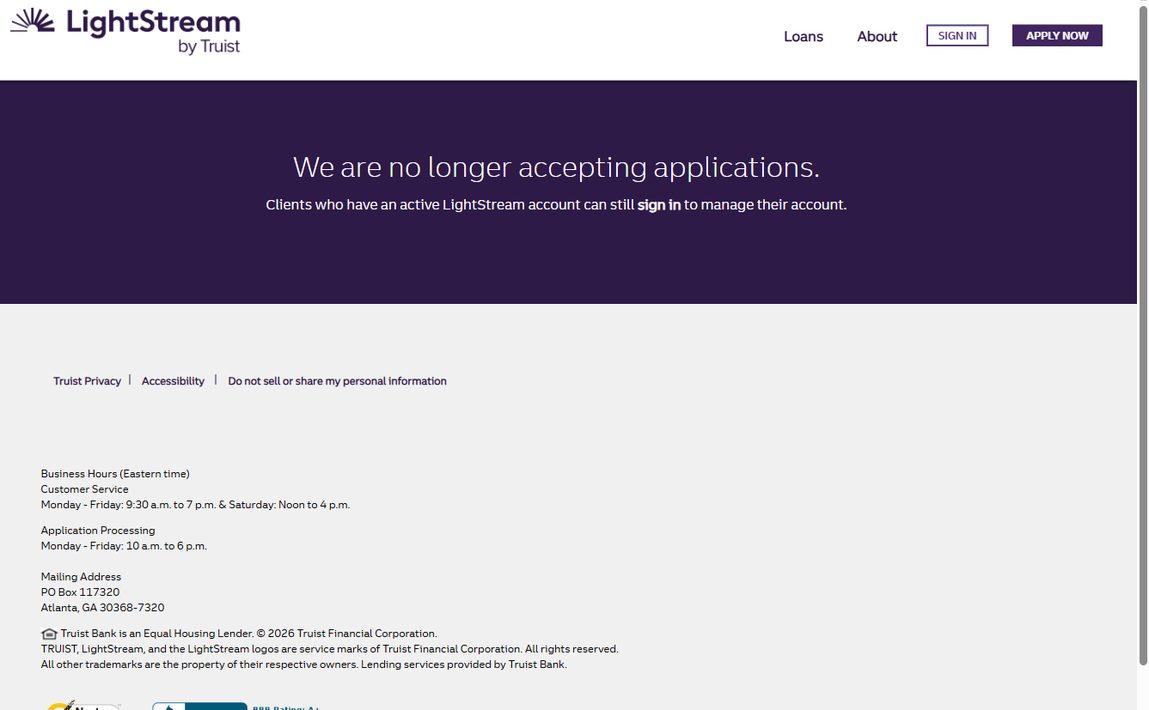
LightStream, a part of the Truist family, offers a different approach by providing loans for practically anything. This is a versatile option for someone who may want to purchase a tractor but prefers the flexibility of a personal loan that isn’t tied to the machine itself.
However, users should take note that availability can shift; currently, they are not accepting new applications for certain products. This makes them a “watch and wait” option for those looking for high-quality, versatile personal lending once their application window reopens.
Pros:
- High degree of flexibility for various purchase types.
- Backed by the stability of Truist Bank.
- Streamlined application process for personal use.
Cons:
- Application availability can be subject to sudden changes or pauses.
7. United
United Bank offers a wide suite of services that include personal, agricultural, and business banking. They are known for providing various ways to manage money, from high-yield CDs to specialized mortgage products, making them a versatile financial home.
While they offer diverse products, their mortgage-related rates—sometimes as low as 5.99% APR—show their capacity for competitive lending. For a farmer looking for a comprehensive banking relationship that covers both equipment and personal assets, they are a solid, FDIC-insured choice.
Pros:
- Comprehensive banking services (Personal, Ag, Business).
- FDIC-insured and backed by the U.S. Government.
- Competitive interest rates on various financial products.
Cons:
- May require a more traditional banking relationship to access best rates.
Avoiding Common Financing Pitfalls
Before signing any paperwork, it is vital to look past the monthly payment and examine the total cost of ownership. A lower monthly payment often comes at the expense of a longer term, which means you will ultimately pay much more in interest over the life of the loan. Always ask for the total amount payable over the full term of the agreement.
Another common mistake is failing to match the loan type to the asset. Using a personal loan to buy heavy farm machinery can sometimes result in higher interest rates than a secured agricultural loan. Similarly, ensure you understand whether the lender requires a down payment or if they offer $0 down options that might suit your current cash flow better.
Finally, do not ignore the fine print regarding prepayment penalties. If you have a particularly profitable season and want to pay off your tractor early to clear your debt, you should ensure the lender won’t charge you a penalty for being responsible. Knowing these details upfront will save you from significant frustration when it comes time to settle your accounts.