
Top 5 Lenders for Bad Credit Loans in North Carolina: 2026 Rankings
Last updated: 2026-11-08
Trying to manage money in North Carolina can feel like driving through a thick Carolina fog without any headlights. For many residents, a bruised credit score acts like a heavy anchor, dragging down the ability to handle urgent repairs, medical bills, or a car that suddenly stops running. Finding a lender that looks at more than just one single number can mean the difference between staying afloat or sinking into more stress.
Whether you are stuck in the middle of a busy Charlotte street or living along the Wilmington coast, the need for quick cash is a reality for thousands. When you start looking for a way out, the goal is to find a balance between how easy it is to get the money and how much it actually costs you. You have to watch out for “easy approval” offers because they often come with a much higher price tag in the form of interest rates.
A loan that solves a problem today might end up costing you a fortune over time because of the Annual Percentage Rate (APR). This list breaks down the most reliable options for North Carolinians dealing with subprime lending markets. We’ve mapped out the various digital and physical paths available to help you find the right direction.
- CreditNinja
- Addition Financial
- JetzLoan
- LoanStart
- OneMain Financial
Evaluating Lenders Across the Tar Heel State
Picking a lender in North Carolina takes a bit more work than just a quick Google search. To put this list together, we measured different providers by how well they work with people who have less-than-perfect credit. We looked at how fast the money actually hits your bank account and whether the application process feels like a marathon or a quick sprint.
Getting access to cash is the most important part of this evaluation. We focused on how many hurdles, like endless paperwork or the need to visit a physical office, stand between you and your funds. We also weighed how flexible the repayment terms are and if the lenders are honest about their costs from the very beginning.
Some lenders live entirely online, using algorithms to make decisions in seconds. Others give you the comfort of a local branch where you can sit down and talk to a real person. This distinction matters. If you live in a rural area, a digital lender might be your only shot. If you are in a big city, having a local office to visit might give you more peace of mind.
| Lender Name | Loan Amounts | Funding Speed | Credit Requirements | Terms |
|---|---|---|---|---|
| CreditNinja | Up to $5,000 | Same day* | Not only credit score | See site |
| Addition Financial | Up to $5,000 | See site | See site | See site |
| JetzLoan | See site | See site | See site | See site |
| LoanStart | Up to $40,000 | See site | See site | See site |
| OneMain Financial | $1,500 – $35,000 | As soon as 1 hour | See site | See site |
Top Ranked Lenders for North Carolina Borrowers
1. CreditNinja
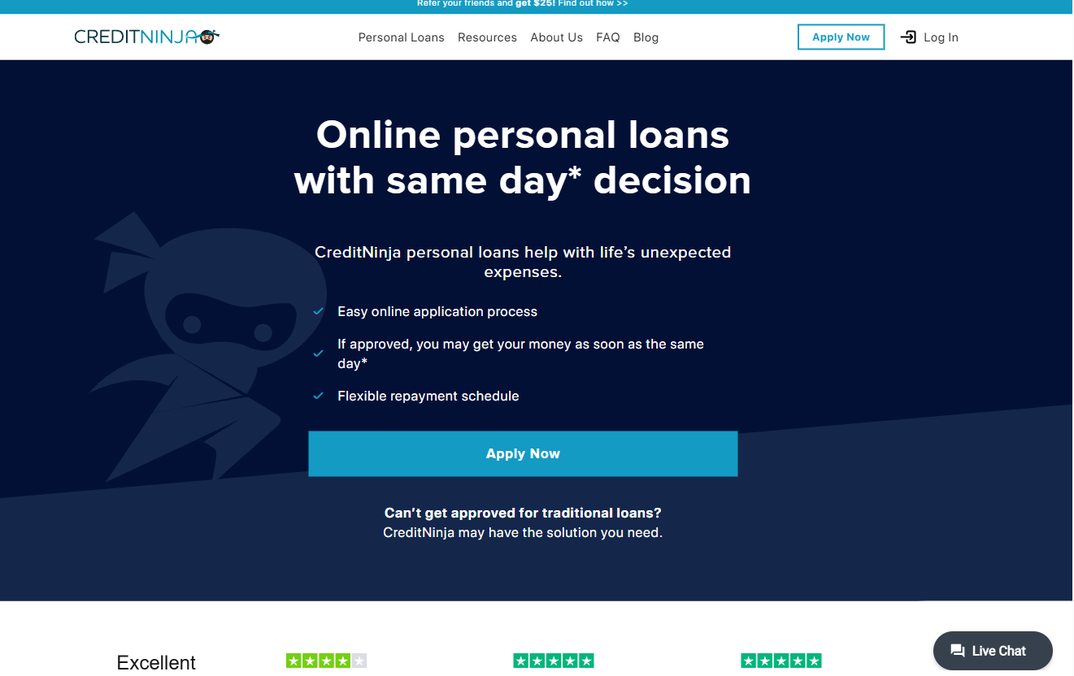
CreditNinja works as a fast digital door for people who find traditional banks are a total brick wall. Their system is built for speed. They use an online application that looks at more than just your credit score to see if you qualify. By checking things like your income stability and how long you have had your job, they offer a path for people whose credit score doesn’t show the whole picture.
If you get the green light, the speed is hard to beat. You could see the money in your account as early as the same day you sign the paperwork. This is a lifesaver when an emergency strikes, like a burst pipe in a Raleigh rental or an urgent car repair that you need to get to work the next morning.
Pros:
- Fast, same-day decision making processes.
- Application considers factors beyond just credit scores.
- Simple and quick online application process.
Cons:
- Does not guarantee approval for all applicants.
- Digital-only interface may lack human connection.
2. Addition Financial
Addition Financial feels more like a traditional banking experience because of its credit union structure. This usually means they focus more on the community than a massive, impersonal national bank. Since credit unions are owned by their members, their goal is often to help the people who use them rather than just making a profit for shareholders. They offer everything from basic checking to more complex personal loans.
If you want to improve your financial health over time, this place offers credit cards and savings accounts too. While we are looking at bad credit options, their membership model is built for long-term stability instead of just a quick cash fix. A North Carolinian might find value in building a relationship with a lender that understands the local economy.
Pros:
- Diverse range of financial products and services.
- Credit union model often provides competitive rates.
- Opportunities for long-term savings and growth.
Cons:
- Membership requirements may limit accessibility.
- May not be as fast as purely digital lenders.
3. JetzLoan
JetzLoan is a specialized option for people looking for specific loan setups. They don’t have the massive footprint of a huge bank, but they try to fill the gaps left by traditional lenders. Those big banks often turn their backs on high-risk borrowers. JetzLoan takes a more tailored approach, focusing on what the specific applicant needs instead of a rigid, one-size-fits-all policy.
Finding the right loan can feel like finding a needle in a haystack, and JetzLoan fits a very specific niche. They are a good choice if you have already been told “no” by your local bank. Their model is built for the borrower who needs a non-traditional way to get cash without jumping through all the heavy bureaucratic hoops of a major institution.
Pros:
- Targeted lending solutions for specific needs.
- Alternative to traditional bank denials.
- Potential for specialized loan structures.
Cons:
- Limited public information on specific terms.
- Availability may vary by region.
4. LoanStart
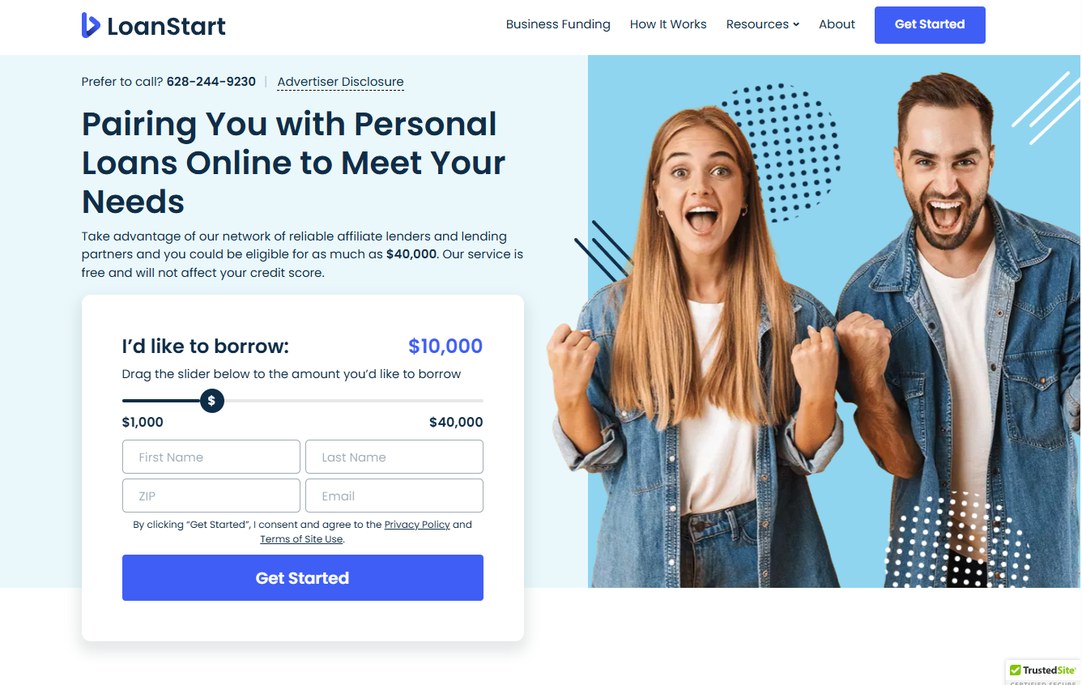
LoanStart works as a bridge between borrowers and a huge network of different lenders. They aren’t actually a single lender themselves. Instead, they act as a matching service. This can help you get much higher borrowing limits than a small lender could offer, because the platform searches through many sources to find the best match for your profile.
You can request amounts up to $40,000 through their platform. This makes it a real option for big expenses like debt consolidation or fixing a roof. If a homeowner in Asheville needs $20,000 for a major repair, LoanStart’s network is much more likely to find a lender that can handle that amount than a small-scale payday lender would be.
Pros:
- Access to a wide network of multiple lenders.
- High borrowing limits up to $40,000.
- No cost to use the matching service.
Cons:
- You are being matched, not guaranteed a specific rate.
- The process involves multiple third-party lenders.
5. OneMain Financial
OneMain Financial is a major player in the personal loan world, especially for people who want to talk to a human. With over 1,300 branches, they have a physical presence that online lenders can’t match. This is great if you prefer to sit across a desk from a real person, explain your situation, and get some guidance during the application.
They provide large loan amounts, from $1,500 all the way up to $35,000. If you sign your papers, you could see that money in your account in as little as an hour. Their fixed monthly payments make it much easier to plan your monthly budget, which is a huge help when you are trying to recover from a financial setback.
Pros:
- Extensive branch network for in-person support.
- Very fast funding, potentially within one hour.
- Fixed monthly payments for easier budgeting.
Cons:
- Interest rates can be higher for those with poor credit.
- Branch visits may require more time than online apps.
Understanding the Real Cost of Credit
When you look at a loan, don’t just look at the monthly payment. You have to look at the total cost of borrowing the money. This is where many North Carolina borrowers get hit with unexpected stress. You need to look closely at two numbers: the Interest Rate and the Annual Percentage Rate (APR).
The interest rate is what you pay each year to borrow the principal. However, the APR is a much more honest number because it includes the interest rate plus any other fees, like processing or documentation costs. A loan might look cheap because of a low interest rate, but if there are heavy upfront fees, the APR might be much higher. Always compare loans using the APR to see what you’ll actually pay over the life of the loan.
Imagine Lender A offers a $5,000 loan at 15% interest with no fees. Lender B offers that same $5,000 at 12% interest but charges a $500 fee. Even though Lender B has a lower rate, that $500 deduction might make Lender A the cheaper choice in the long run. Always ask for a “Truth in Lending” disclosure. It’s a standard form that tells you exactly how much you will have paid back by the end of the term.
Strategies for Improving Your Borrowing Position
Getting a loan solves a problem today, but many people end up stuck in a cycle of debt because they don’t have a plan for tomorrow. If you are borrowing to cover a gap, you should also be trying to make sure you don’t need to do this again. There are several ways to strengthen your financial profile right now in North Carolina.
First, watch your “Credit Utilization.” If you have credit cards, try to keep your balances below 30% of your total limit. If your limit is $1,000, try to keep the balance under $300. This is one of the fastest ways to boost your score, which eventually leads to much lower interest rates on your next loan.
Second, pay attention to your “Payment History.” A single late payment can tank your score. If you are struggling, call your lender or utility company *before* you miss a deadline. They often have hardship programs or can defer a payment. You might also consider a secured credit card. You put down a cash deposit that acts as your limit, allowing you to build credit safely without overspending.
Navigating the Lending Landscape Safely
The biggest danger for North Carolina borrowers is the “quick fix” trap. It is easy to get excited about an instant approval, only to realize later that the interest rate is a mountain you can’t climb. Always read the fine print on the APR and any hidden fees before you sign anything. Watch out for “prepayment penalties” too. Some lenders charge you a fee just for being responsible and trying to pay the loan off early.
Stay away from anyone promising “guaranteed approval.” If it sounds too good to be true, it usually is. In the money world, everything has a catch. If a lender says they won’t check your info, they are likely charging a massive premium that will keep you in debt for years. Real lenders will always check your income or your credit to make sure you can pay them back.
If your credit is very low, you might want to look into a co-signer or ask for a smaller loan amount. This makes the lender feel safer and can get you a better rate. If a family member with good credit vouches for you, it can help, but remember they are legally responsible for the debt too. If you don’t pay, their credit gets ruined along with yours. A loan is a tool; used right, it builds a foundation, but used poorly, it becomes a burden that is very hard to shake.