
Top 6 Lenders for Personal Loans for Credit Score Under 600 in 2026
Last updated: 2026-11-08
Trying to find a lender when your credit score sits below 600 feels like walking through waist-deep mud. Most big banks will politely show you the door. Their models rely on old data and strict risk rules, which often treat a low score like a permanent barrier instead of a temporary hurdle.
Fortunately, the financial world in 2026 has changed. New players are looking past that single number to see if you are actually reliable. They might check if you pay your utilities on time, how you handle rent, or the steady flow of cash in your checking account to build a real picture of your creditworthiness.
When your score is bruised, your priority shifts. You aren’t chasing the absolute lowest interest rate anymore; you are just looking for someone to say “yes.” A high-score borrower might obsess over a 2% difference in APR, but someone with a 550 score is often just relieved to get approved at all.
You have to weigh how fast you get the money against what it costs you in the long run. A quick $1,000 might save you from a $35 late fee on a utility bill today, but a bad loan with high compounding interest can turn into a debt spiral. This list focuses on lenders that actually show up when your credit report looks rough.
- Upgrade
- Avant
- FastLendGo
- NetCredit
- Credit Ninja
- Elite Personal Finance
How These Lenders Were Evaluated
We looked specifically for lenders that accommodate people with fair or poor credit. Since a score under 600 can mean different things depending on whether you use FICO or VantageScore, we prioritized companies that use diverse underwriting. We wanted lenders that look at your employment stability or your debt-to-income ratio through tools like Plaid instead of just glancing at one number.
Speed matters. If your car transmission fails or you have an urgent medical bill, a slow approval is useless. We also checked for transparency. You need to know exactly what the loan costs before you sign anything. We sought out lenders that lay out every origination fee and interest schedule clearly so there are no surprises later.
| Lender Name | Loan Amount | Max APR/Terms | Funding Speed | Credit Requirements |
|---|---|---|---|---|
| Upgrade | Up to $50,000 | See site | Fast funding | 600+ score |
| Avant | See site | See site | See site | 580+ score |
| FastLendGo | $500 – $5,000+ | See site | Quick access | Bad credit options |
| NetCredit | Up to $10,000 | See site | Same-day available | Advanced algorithms |
| Credit Ninja | See site | See site | Same-day decision | Flexible schedule |
| Elite Personal Finance | Up to $5,000 | 15% to 20% | 5-minute approval | 400 – 500 score |
1. Upgrade
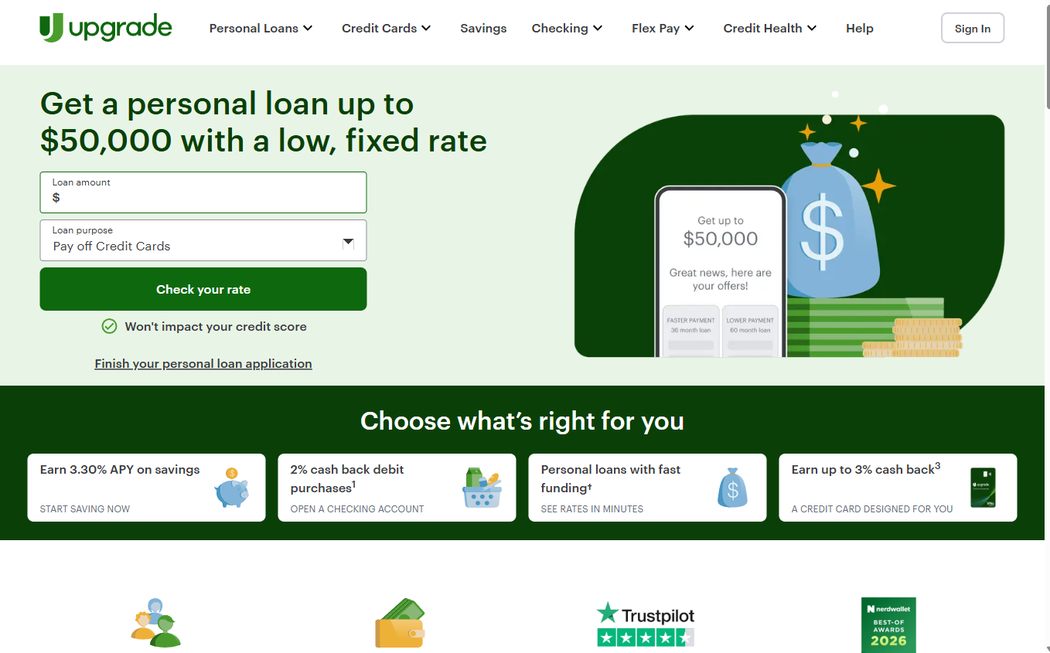
Upgrade is more than a loan provider; they act as a full-service financial hub. They offer credit cards and rewards checking accounts alongside personal loans. This makes them a good fit if you want to manage everything in one place and build a longer relationship with your lender.
If you use an Upgrade credit card responsibly for six months, that good behavior can help when you eventually apply for a larger personal loan through them. They cover everything from debt consolidation to big home improvements. It is a convenient way to keep your finances under one roof without switching between a dozen different apps.
Pros:
- Large loan amounts up to $50,000
- Options for debt consolidation and large purchases
- Fast funding capabilities
Cons:
- Requires a 600 credit score for certain products
2. Avant
Avant is built for people who need to keep moving despite a bumpy financial past. They understand that life happens, and they are willing to work with scores as low as 580. While a traditional bank might just reject you for being under 650, Avant looks deeper at your income stability and current debt load.
Their products are designed for real-life situations, like a sudden medical bill or needing to consolidate debt to lower your monthly bills. They aim to provide clear answers and structured repayment plans. This helps you work toward better financial health rather than feeling like you are stuck in a cycle of debt.
Pros:
- Approves borrowers with scores as low as 580
- Requires a relatively low monthly income of $1,200
- Flexible loan solutions for various needs
Cons:
- Terms and rates are not explicitly detailed upfront
3. FastLendGo
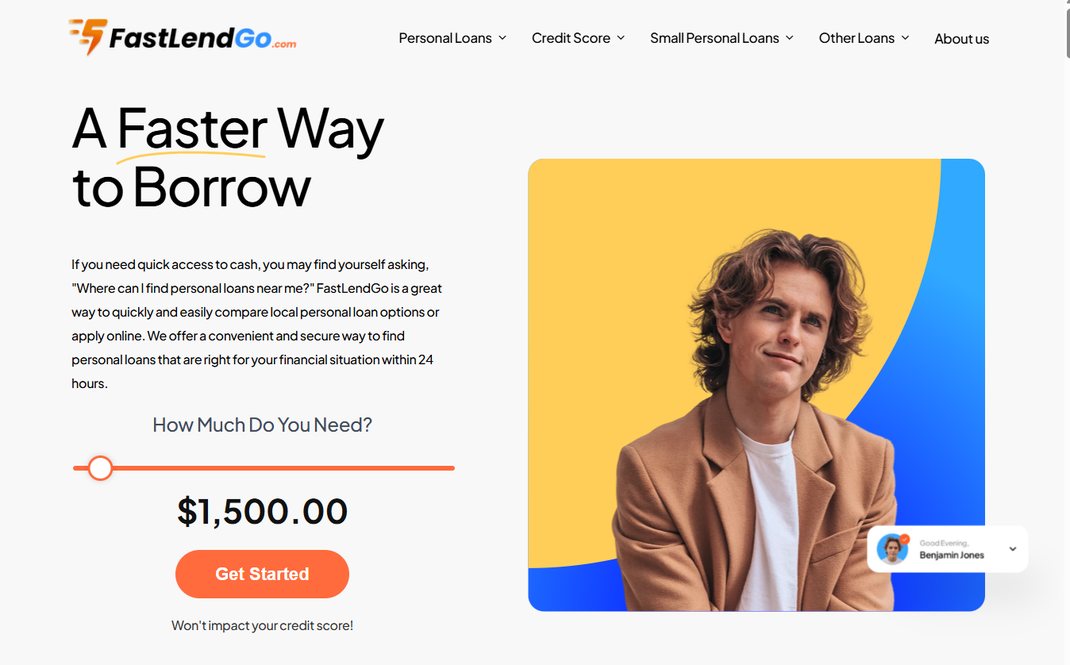
FastLendGo works well when you need cash for a very specific, immediate problem. They specialize in scenarios like car repairs or dental work. If your car’s alternator dies and you need it fixed by tomorrow to get to work, FastLendGo is built for that kind of urgency without the bank’s red tape.
They offer set amounts like $500, $1,000, or $5,000. This makes it easy to match the loan to the actual cost of the repair. It is much better than taking out a giant $10,000 loan and paying interest on money you don’t even need. You can just target the exact amount required for the job.
Pros:
- Specific loan amounts available for various needs
- Covers niche expenses like dental or roof financing
- Quick online comparison and application
Cons:
- Focuses heavily on small-dollar quick-access loans
4. NetCredit
NetCredit looks at the person, not just a number in a database. They use advanced algorithms to check your employment consistency and bank history. This is a huge help if your score is low because of a past mistake, but you have a stable income right now. They see that you are a low-risk borrower in the present.
They offer same-day funding, which is great when time is tight. The application is simple and uses a soft credit pull. This means you can see if you qualify without hurting your FICO score. You can shop around and compare options without the fear of making your credit situation even worse.
Pros:
- Same-day funding available
- Check eligibility without impacting FICO score
- Uses advanced algorithms for holistic review
Cons:
- Loan amounts are capped at $10,000
5. Credit Ninja
Credit Ninja is a streamlined option for people who want a quick decision. They focus on those “unexpected expenses” like a plumbing emergency or a sudden vet bill. Their application process is fast and easy, removing much of the stress that usually comes with getting a loan.
The speed here is impressive. Once you are approved and sign the paperwork, you could see the money in your account the same day, depending on your bank. If your car breaks down on a Tuesday, you can have it fixed quickly. They provide customized offers tailored specifically to your unique financial situation.
Pros:
- Same-day decision and potential same-day funding
- Quick and simple online application
- Flexible repayment schedules
Cons:
- Availability of funds depends on direct deposit timing
6. Elite Personal Finance
Elite Personal Finance is for those with very difficult credit profiles. They specifically target the 400 to 500 score range. This provides a lifeline for people who might be shut out by traditional banks because of a past bankruptcy or a period of delinquency. They act as a safety net when things are tough.
They are a real alternative to predatory payday loans, which often have interest rates exceeding 400%. Elite Personal Finance offers regulated, secure options so you don’t fall into a “debt trap.” Their process is incredibly fast, with approvals sometimes coming in just five minutes.
Pros:
- Accepts very low credit scores (400-500)
- Extremely fast approval process
- Alternative to payday loans
Cons:
- Higher APRs ranging from 15% to 20%
The Real Cost of Fast Cash: APR vs. Total Interest
When you are in a rush, you might only look at the monthly payment. A $50 monthly payment sounds easy, but if that is spread over 48 months at a 35% APR, you will pay back nearly double what you borrowed. This is the “interest trap” that many people with low scores fall into.
You have to look at the Total Cost of Loan. This is the sum of every monthly payment you will make over the life of the loan. It is the most important number for your long-term budget.
Consider this comparison:
| Scenario | Loan Amount | Monthly Payment | Total Interest Paid |
|---|---|---|---|
| Option A (Low Rate) | $3,000 | $150 | ~$600 (36 months) |
| Option B (High Rate) | $3,000 | $110 | ~$2,280 (36 months) |
As the table shows, Option B has a lower monthly payment, which feels better today. However, the total cost to your future self is much higher. Always ask: “Can I afford the total cost, or just the monthly payment?”
How to Use a Sub-600 Loan to Build Your Score
If you use a loan to handle an emergency, try to view it as a tool for credit repair. The goal is to prove to future lenders that you are a reliable borrower. Here is a way to make that happen:
- Set Up Auto-Pay: A single missed payment can destroy your progress. Even if you only set up auto-pay for the minimum amount, it ensures you are never late.
- Pay More Than the Minimum: If you can, paying an extra $20 toward the principal each month can shave months off the loan and lower your total interest.
- Avoid New Debt: While you are paying this off, try not to open new lines of credit. Keeping your “credit utilization” low is key to seeing a score increase.
- Monitor Your Progress: Use a free service to track your score. As it moves from 580 toward 620, you might eventually be able to refinance into a much cheaper loan.
Avoiding Pitfalls When Borrowing
Always read the fine print before you sign anything. It is easy to get excited about a quick approval, but the total cost of credit is what actually matters. Check for hidden fees or prepayment penalties. A prepayment penalty is a fee a lender charges if you try to pay the loan off early; you want to avoid these so you can save money as your credit improves.
Don’t borrow more than you can realistically repay. Just because a lender offers you $5,000 doesn’t mean your budget can handle it. Use a loan calculator to see how the payment fits your lifestyle. If your rent and food already eat up 70% of your income, a $200 loan payment might push you into a deficit. Plan for the worst-case scenario, like a drop in work hours, to make sure you stay ahead of your bills.