
Top 5 Lenders for First Time Personal Loans With No Credit History in 2026
Last updated: 2026-11-08
Walking into the world of borrowing can feel like stumbling into a dark room without a flashlight. If you are staring at a blank credit report, the traditional banking gates often seem bolted shut. It is a frustrating cycle where you need credit to prove you are trustworthy, yet you cannot get credit without a history. This financial catch-22 often leaves young adults, recent immigrants, or those recovering from financial setbacks feeling paralyzed by a lack of options.
The landscape has shifted significantly, however. Many lenders now look past that empty score to evaluate your actual behavior. They might peek at your steady paycheck, your history of paying utility bills, or even your consistency in paying rent. This transition from traditional credit scoring to “alternative data” modeling has opened doors for millions. Finding the right partner depends on knowing which lenders value your potential more than your past.
- VivaLoan
- FastLendGo
- OneMain Financial
- GreendayOnline
- SoFi
How These Lenders Were Evaluated for New Borrowers
The selection process focused on accessibility and speed. For someone without a credit history, a slow approval process is a dealbreaker. A lender must be able to make a quick decision based on alternative data rather than just a three-digit number. Speed is the heartbeat of emergency financing, especially when a car repair or a medical bill cannot wait for a thirty-day manual underwriting process.
Another critical factor was the flexibility of loan amounts and the ease of the application. Some lenders cater to tiny, emergency needs—often called “microloans”—while others are built for larger life milestones like debt consolidation or home improvement. This ranking weighs the ability to get funds quickly against the total amount available to a first-time borrower, while also considering the friction involved in the digital application journey.
| Lender Name | Loan Amounts | Funding Speed | Credit Requirements |
|---|---|---|---|
| VivaLoan | $100 – $15,000 | As soon as tomorrow | All credit types welcome |
| FastLendGo | See site | Quick access | Bad, fair, and good credit |
| OneMain Financial | $1,500 – $35,000 | As soon as 1 hour after signing | No credit score impact for offers |
| GreendayOnline | $100 – $5,000 | Same day | Bad credit welcome |
| SoFi | See site | See site | See site |
Top Rated Lenders for Building Credit and Fast Cash
1. VivaLoan
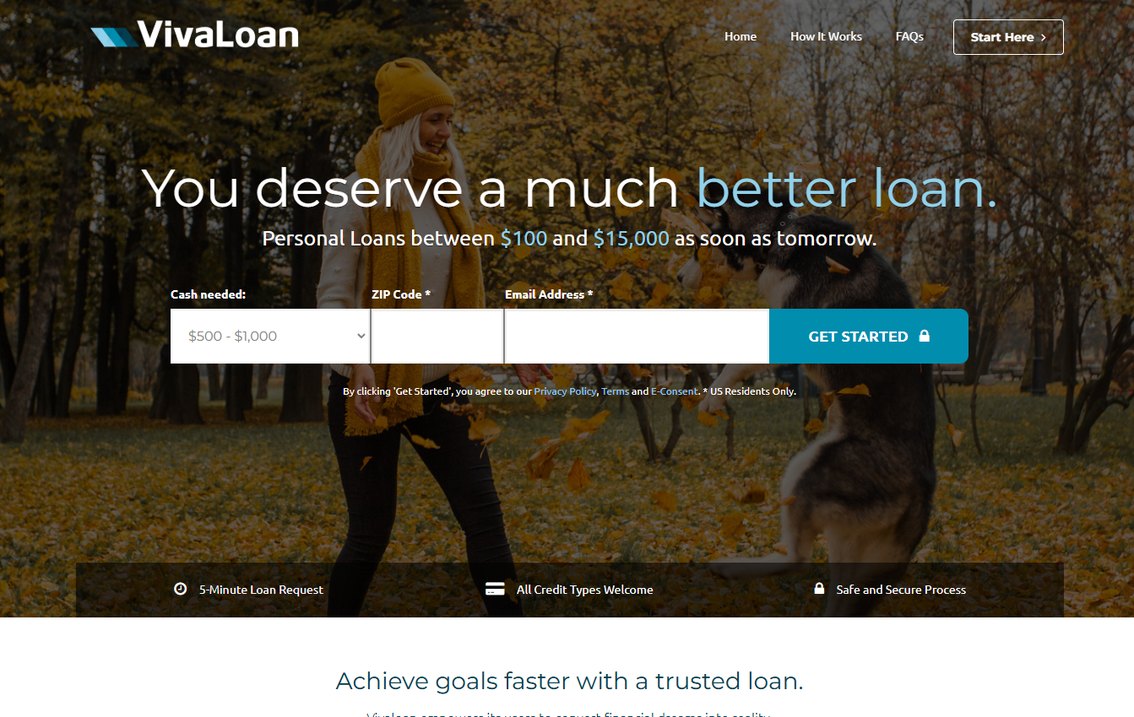
VivaLoan helps those trying to turn financial dreams into reality. They offer a range of options starting from as little as $100 up to $15,000. It is a versatile choice for someone who might need a small boost for a quick repair or a larger sum for a major life event. Because their limits are tiered, you can start small to test the waters and grow your relationship with the lender as your credit score improves.
The speed of this lender is hard to beat for a first-time borrower. Once the request is processed, funds typically land in your account as soon as the next business day. This makes it a reliable option when you cannot afford to wait weeks for a decision. Their digital-first approach removes much of the bureaucratic red tape often found in legacy banks.
Pros:
- Extremely fast funding, often as soon as tomorrow.
- Broad range of loan amounts from $100 to $15,000.
- Welcomes all credit types, making it ideal for no-history users.
Cons:
- Limited to US residents only.
2. FastLendGo
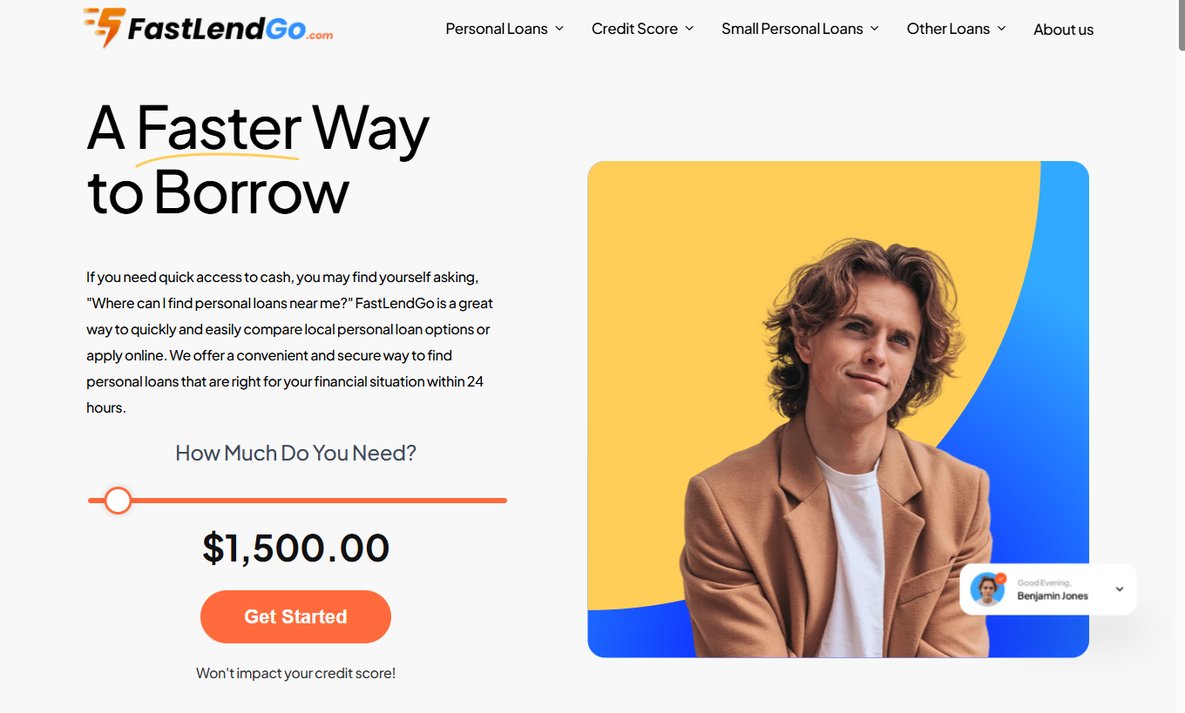
FastLendGo acts as a partner in personal financing, offering a variety of specialized loans. Whether you are looking for a $500 loan for an emergency or a $5,000 loan for a larger project, they cover a wide spectrum. They even offer specific options for auto or dental financing, which is particularly beneficial for those who need to secure a specific asset to avoid further debt. (fastlendgo.com)
This lender is particularly useful if you are searching for a way to compare local options quickly. They cater to a wide range of financial standings, from those with bad credit to those with great credit. This flexibility means you won’t be automatically disqualified by a single low score if your income and employment history are strong.
Pros:
- Specialized loan types for specific needs like auto or roof repair.
- Covers a wide range of credit scores from bad to great.
- Provides quick access to cash.
Cons:
- The selection of available states may limit some users.
3. OneMain Financial
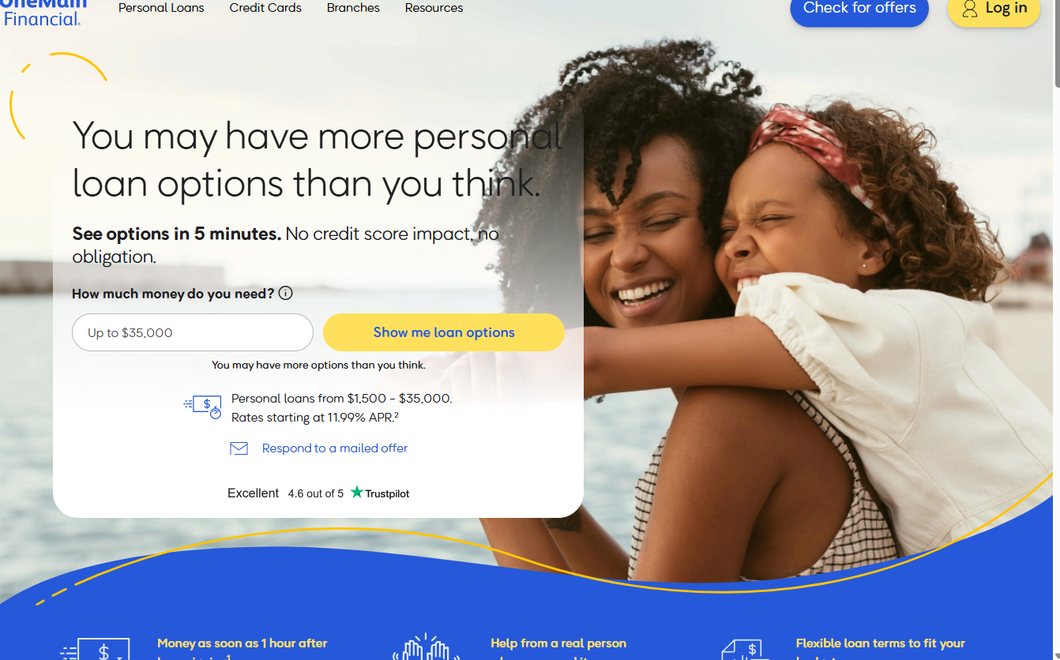
OneMain Financial is a powerhouse for those who need significant capital. With loans reaching up to $35,000, they offer much more weight than a typical small-scale lender. They provide a human touch through their 1,300 physical branches. This is a relief for those who prefer talking to a real person or who may find complex digital forms overwhelming. This physical presence provides a layer of security and accountability often missing in purely online lending.
If you are in a time crunch, their speed is impressive. You can see your options in about five minutes, and money can arrive as soon as one hour after the loan is signed. This is a heavyweight option for serious financial moves, such as consolidating high-interest credit card debt into a single, manageable monthly payment.
Pros:
- Large loan amounts up to $35,000.
- Extremely fast funding, potentially within an hour of signing.
- Access to physical branches for personal assistance.
Cons:
- Rates start at 11.99% APR, which may increase based on profile.
4. GreendayOnline
GreendayOnline is a go-to for the “right now” moments. They specialize in small payday-style installment loans ranging from $100 to $5,000. If you are facing an unexpected bill—such as an urgent utility shut-off notice or a sudden repair—and need cash today, this lender is designed specifically for that high-pressure situation. They prioritize immediate liquidity over long-term financing.
The application process is streamlined to be incredibly simple. You fill out a short online form, and because they do not perform hard credit checks, you can find out where you stand without risking your score. This “soft check” mechanism is crucial for newcomers who are trying to gauge their options without further complicating their credit profile.
Pros:
- No hard credit checks during the process.
- Same-day money availability.
- Simple and fast online application.
Cons:
- Loan amounts are relatively small, capped at $5,000.
5. SoFi
SoFi is more than just a lender; it is a comprehensive financial ecosystem. While they are a major player, they offer a sophisticated suite of tools including high-yield savings and investment options. They are best suited for those looking to build a long-term financial foundation rather than just solving an immediate cash shortage. Their platform is designed to grow with you from your first loan to your first mortgage.
While they may be more selective than some of the other lenders on this list, their platform is incredibly polished. For a first-time borrower looking to move into more advanced banking products, SoFi provides the infrastructure to grow alongside your credit score. They are an excellent choice if you have a stable income and are looking to transition from “emergency” borrowing into “wealth-building” banking.
Pros:
- Comprehensive financial tools including banking and investing.
- Integrated experience for managing money and savings.
- Polished, modern digital interface.
Cons:
- May have stricter requirements than specialized “no credit” lenders.
Understanding the Real Cost of Borrowing
Many first-time borrowers focus exclusively on the monthly payment, but this is a dangerous way to evaluate a loan. To truly understand what you are paying, you must look at the Annual Percentage Rate (APR). The APR includes not just the interest rate, but also any origination fees or administrative costs that the lender might tack on. For example, a loan with a 10% interest rate and a $500 origination fee might actually be more expensive than a loan with a 12% interest rate and no fees.
Consider the “Total Cost of Loan” calculation. If you borrow $1,000 and agree to pay it back over 24 months at 25% APR, your monthly payment might seem manageable, but you will end up paying back nearly $1,450 in total. That extra $450 is the price of convenience. When comparing lenders, always ask for a breakdown of the total amount you will have paid by the end of the term. This comparison is the most effective way to determine if a lender is offering a fair deal or a predatory trap.
Strategies for Using Loans to Build a Credit Score
A personal loan can be a powerful engine for credit growth if used strategically. When you have no credit history, your “payment history” and “amounts owed” are the two most significant factors in your score. By taking out a small, manageable loan and paying it back perfectly, you are essentially “buying” a history of reliability. This is often more effective than waiting years to build history through credit cards, which can be harder to manage due to fluctuating interest and revolving balances.
To maximize this benefit, follow these three tactical steps:
- Set Up Autopay: Even one missed payment can tank a nascent credit score for months. Autopay ensures that your “on-time payment” streak remains unbroken, regardless of your schedule.
- Pay Early or On-Time: Never wait until the due date. Paying a few days early shows the lender (and your credit report) that you are proactive, not just reactive.
- Avoid “Credit Maxing”: If you use a loan to pay off credit cards, do not immediately go out and run up those credit card balances again. This creates “double debt,” where you owe the loan and the cards simultaneously, which can lead to a downward spiral.
Finally, remember that a personal loan is a tool, not free money. For a first-time borrower, the best way to use this tool is to build a history of on-time payments. Treat your loan like a training ground; paying it back exactly as scheduled is the fastest way to ensure you never have to look for “no credit” options again. As your score climbs, you will find that the “gates” of traditional banking swing wide open, offering you lower rates and much larger sums of capital.