
Top 5 Lenders for Bad Credit Loans in Arizona for 2026
Last updated: 2026-11-08
Surviving the desert heat is hard enough, but a sudden financial crisis in Phoenix or Tucson can feel even more blistering. When your credit score takes a hit, finding a lifeline that won’t drain your bank account dry becomes the ultimate goal for many Arizona residents.
Maybe you are facing an unexpected medical bill in Mesa, an urgent car repair in Scottsdale, or a sudden rent shortfall in Tempe. The pressure to find quick cash often clashes with the need to avoid predatory lending traps.
Selecting the right lender requires looking past the flashy advertisements. It is about finding a balance between speed, accessibility, and the long-term cost of borrowing when your options feel limited by past mistakes. It is not just about getting the cash today; it is about ensuring that the cash doesn’t come with a cost that cripples your financial future next month.
- OneAZ
- Arizona Zip Loan
- PaydayChampion
- Credit Union West
- SkyOne
Evaluating Financial Assistance Across the Grand Canyon State
To determine which lenders provide the most viable paths for those with less-than-perfect credit, several specific metrics were analyzed. The primary focus remained on how accessible these funds are for residents living from Sedona to Yuma. Availability of quick approval is a major factor when emergencies strike, such as an HVAC failure during a Maricopa County heatwave.
Loan amounts and the flexibility of repayment terms also played a massive role in this ranking. A lender might offer fast cash, but if the interest rates are predatory, they fail the test of true utility. We looked at the difference between “flat fees” and “Annual Percentage Rates (APR),” as the latter provides a much clearer picture of the actual cost of borrowing.
This evaluation prioritizes lenders that offer clear structures and recognizable Arizona-based service models. We chose transparency over marketing jargon to help you see exactly what you are getting into.
| Lender Name | Loan Amounts | Key Feature | Credit Requirement |
|---|---|---|---|
| OneAZ | See site | Credit Union Services | Low credit scores considered |
| Arizona Zip Loan | $1,000 – $35,000+ | Fast as a desert breeze | See site |
| PaydayChampion | $100 – $5,000+ | No credit checks | No credit check options |
| Credit Union West | See site | Disaster Relief options | See site |
| SkyOne | See site | Family-focused tools | See site |
The Arizona Bad Credit Loan Rankings
1. OneAZ
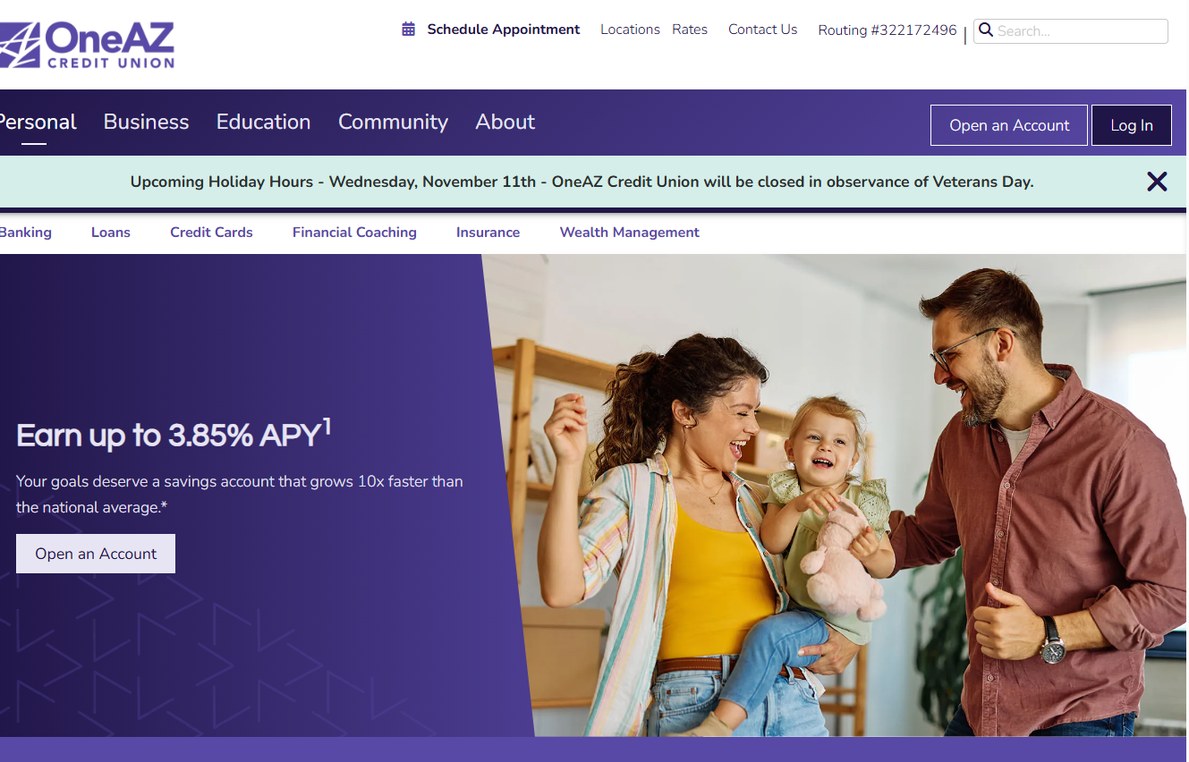
OneAZ stands out as a comprehensive credit union providing more than just simple cash injections. They offer a wide array of banking, loans, and wealth management services that aim to build long-term stability for members. Unlike a traditional payday lender that focuses on a single transaction, OneAZ operates on a membership model designed to grow with you.
It is a practical option for those looking to transition from survival to growth. For those struggling with a rocky history, they offer express personal loans. These amounts can range from $250 up to $15,000, making them suitable for both small emergencies—like a sudden transmission issue—and larger needs, such as consolidating high-interest debt from multiple credit cards.
They specifically consider low credit scores if an account is maintained satisfactorily. They recognize that a single mistake in your credit history doesn’t define your entire financial future. It is about seeing the person, not just the score.
Pros:
- Wide variety of financial products including wealth management.
- Express loan options available for smaller amounts.
- Strong focus on long-term financial coaching.
Cons:
- Requires maintaining a satisfactory account for better odds.
- Application processes may be more rigorous than payday lenders.
2. Arizona Zip Loan
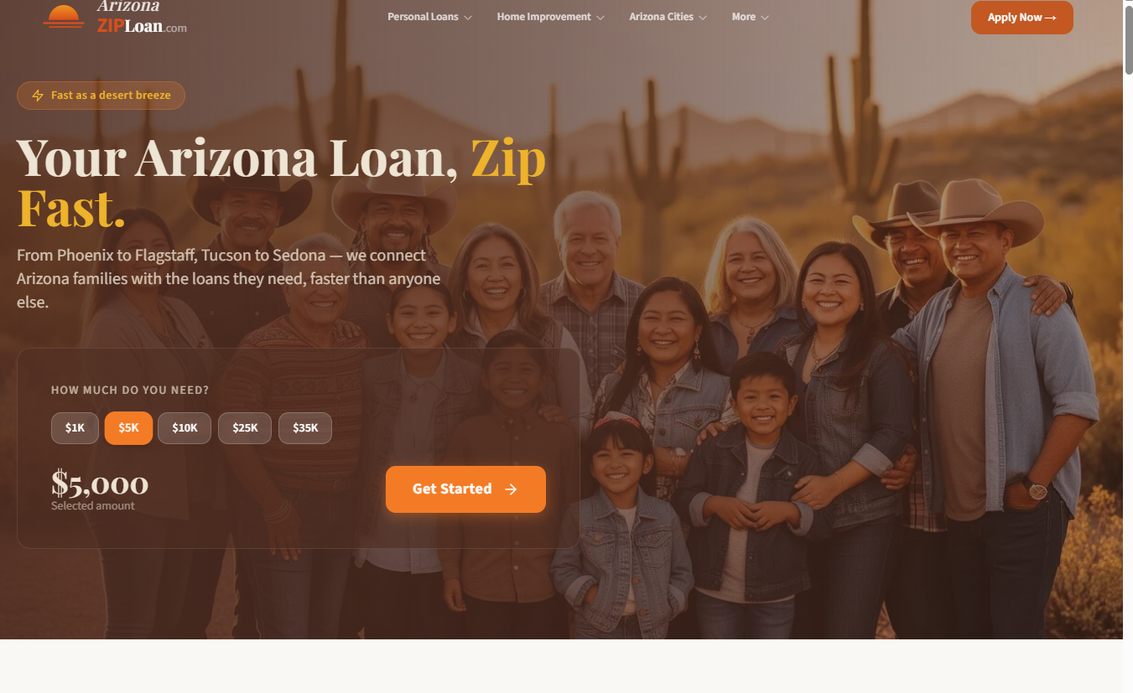
If you are staring at a mounting pile of bills and need money yesterday, this lender focuses on speed. They market themselves as being “fast as a desert breeze,” connecting families from Phoenix to Flagstaff with necessary funds. This lender is designed for the “gap” period—that week between an unexpected expense and your next paycheck when your checking account is running low. (arizonaziploan.com)
The service caters to various needs, including home improvements or medical expenses. With a reported average approval time of 24 hours, they target the segment of the population that cannot afford to wait weeks for a bank’s decision. Their streamlined online interface is built for users who may be accessing the web via a smartphone while on the go.
This ensures that the application process doesn’t become another hurdle in an already stressful day. When you are in a pinch, every minute counts toward your peace of mind.
Pros:
- Rapid 24-hour average approval time.
- High customer satisfaction ratings.
- Large loan range from $1,000 up to $35,000 and beyond.
Cons:
- Speed often comes with different interest rate structures.
- Focus is heavily on speed rather than long-term coaching.
3. PaydayChampion
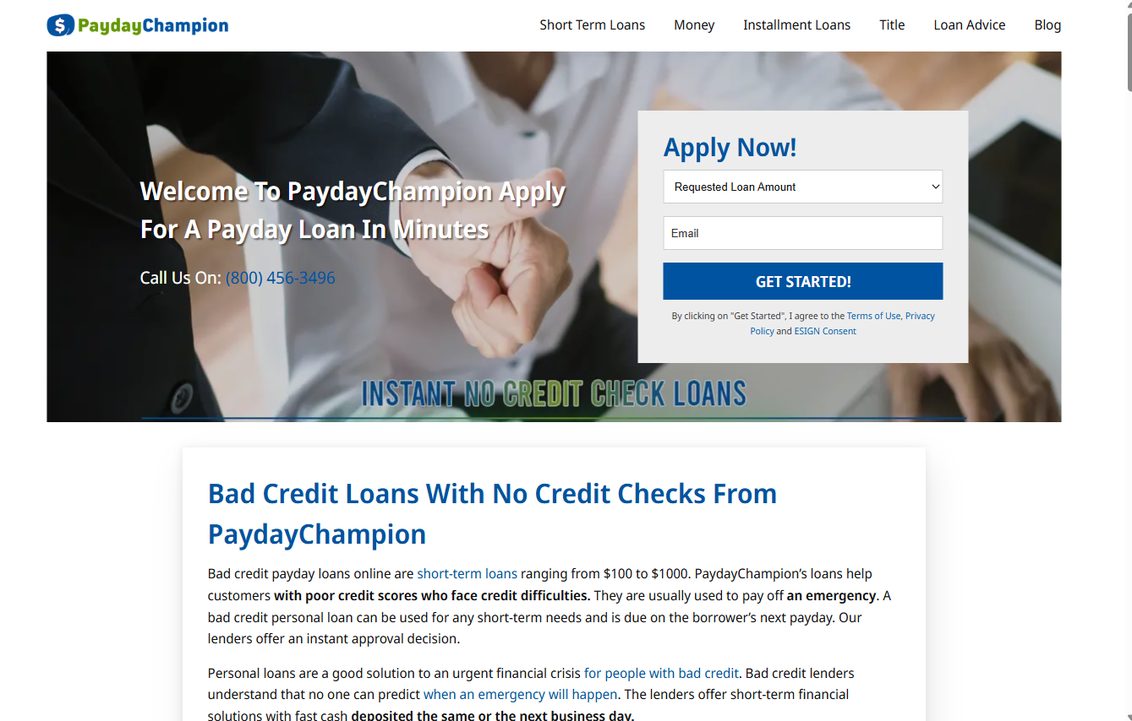
PaydayChampion operates in the fast lane of short-term lending. They specialize in instant, no-credit-check loans that are designed specifically for those facing extreme credit difficulties. This is a “quick fix” solution for immediate emergencies where traditional banks have slammed the door shut due to a low FICO score or a lack of established credit history.
The loan amounts are typically smaller, ranging from $100 up to $5,000 or more. Because they focus on short-term installments, they are best suited for people who know they can pay the money back in the very next pay cycle. For example, if an unexpected $300 utility bill arrives and you won’t get paid for ten days, a small-dollar loan here can bridge that gap.
You can bypass the lengthy scrutiny of a major national bank. It is a specialized tool for a specific type of financial emergency where time is more important than the interest rate.
Pros:
- Extremely high accessibility for those with no credit.
- Quick application process that takes only minutes.
- Wide range of small-dollar installment options.
Cons:
- Short-term nature can lead to a cycle of debt.
- High interest costs are common with no-check loans.
4. Credit Union West
Credit Union West is a stabilizing force for many Arizona residents. While they offer traditional personal loans, they are particularly noted for their community-focused relief efforts. For instance, they provide specific assistance like 0% interest disaster relief loans for eligible members.
This is an invaluable resource for residents recovering from extreme weather events or other unforeseen local emergencies. They offer a variety of borrowing options that include family life loans and personal loans. Their interest rates can be quite competitive, sometimes starting as low as 10.99%.
This makes them a premier choice for those who have a somewhat functional credit history but need a break from high-interest retail credit cards or predatory installment loans. They act more as a financial partner than a mere lender.
Pros:
- Specialized disaster relief assistance for members.
- Competitive interest rates for personal loans.
- Strong community-centric banking model.
Cons:
- Eligibility for special low-interest relief is strictly limited.
- May require more documentation than quick-cash lenders.
5. SkyOne
SkyOne Federal Credit Union approaches lending through a family-oriented lens. They focus heavily on helping families build savings and plan for the future rather than just providing quick cash. Their philosophy is that thriving goes far beyond just having a balance in the bank; it involves having the tools to ensure that balance grows over time.
They offer various tools, including checking and savings accounts that help manage daily life. While they are a full-service institution, their emphasis on “SmartPay” and wealth management makes them more of a partner for long-term financial health than a lender for immediate crisis management.
This is the ideal destination for a resident who has survived a crisis and is now looking to prevent the next one through disciplined budgeting and savings. They focus on the long game rather than the immediate fix.
Pros:
- Excellent tools for long-term savings and wealth building.
- Focus on family financial stability and future planning.
- Comprehensive suite of banking and credit products.
Cons:
- Less emphasis on immediate “emergency” cash for bad credit.
- May not be the first stop for someone in an urgent crisis.
How to Prepare for a Loan Application
Applying for a loan when your credit is not at its peak can be stressful, but being prepared can significantly increase your chances of approval and better terms. Many people walk into applications blind, which is a mistake that leads to unnecessary rejections or higher interest rates.
First, gather your documentation in advance. Even with “quick” lenders, having your recent pay stubs, proof of residence in Arizona, and identification ready will prevent delays. Second, check your own credit report for errors. If a mistake on your report is dragging your score down, disputing it can make a massive difference in the interest rate you are offered.
Finally, determine your exact “need amount.” Borrowing more than you strictly need just to “be safe” is a common mistake that leads to paying interest on money you didn’t actually require. Only take what you need to settle the specific bill at hand.
Understanding the Real Cost of Borrowing
Before you sign any agreement, you must understand the difference between the nominal interest rate and the Annual Percentage Rate (APR). The interest rate is the cost to borrow the principal, but the APR includes all the fees, such as origination fees, documentation fees, and processing costs. In the world of bad credit lending, the APR is the only number that truly matters for your wallet.
Consider this comparison: A $1,000 loan with a 15% interest rate might look affordable. However, if that lender charges a $200 “processing fee” upfront, your actual cost of borrowing is much higher than 15%. Always ask the lender: “What is the total amount I will have paid back by the end of this term?”
If that number is significantly higher than the amount you are receiving, you must weigh whether the immediate relief is worth the long-term expense. Don’t let a low monthly payment blind you to a massive total repayment.
Navigating the Loan Landscape Without Getting Burned
Borrowing money when your credit is low is a bit like walking through a cactus patch; you have to be very careful where you step. The first mistake many people make is ignoring the fine print regarding interest rates. A small loan today can become a massive mountain of debt tomorrow if the APR is not understood. High-interest debt is a compounding force that works against you every single day.
Always compare the total cost of the loan, not just the monthly payment. A lender might promise a low monthly installment, but if the term is incredibly long, you will end up paying back double or triple what you originally borrowed. For example, a 36-month loan with a high APR might result in you paying $2,500 for a $1,000 loan. It is vital to look at the total repayment amount before signing anything.
Another common pitfall is using short-term loans to cover long-term problems. If you use a high-interest payday loan to pay off a credit card, you might find yourself in a worse position next month because the payday loan has much higher interest and a much shorter repayment window. This is known as “robbing Peter to pay Paul,” and it is a primary driver of the debt cycle.
Try to use these funds only for true emergencies—like a broken water heater or a medical procedure—and always have a plan to exit the debt as quickly as possible. Staying ahead of the interest is the only way to win.